
MONTREAL – In a transformative move that signals a significant shift in the Canadian telecommunications landscape, BCE Inc. (Bell), the nation’s largest communications provider, has announced a definitive agreement to monetize a substantial portion of its wireless tower portfolio. The deal sees global investment group La Caisse (CDPQ) acquiring a 49.9% stake in a newly formed entity, colloquially known as "TowerCo," for a purchase price of CAD $2.45 billion.
This transaction, which values the total tower infrastructure at approximately $4.91 billion, represents more than just a capital injection; it is a strategic repositioning of Bell’s balance sheet and a commitment to a new era of infrastructure management in Canada.
I. Main Facts: The Architecture of the Deal
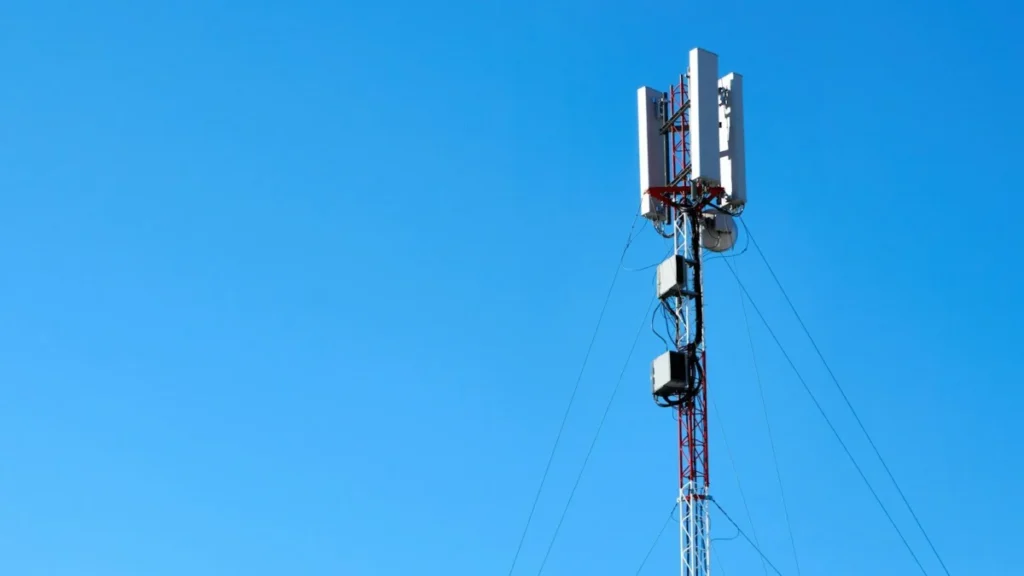
The agreement between BCE and La Caisse is structured to surface the latent value of Bell’s "passive" infrastructure—the physical steel and concrete towers that house the sensitive electronic equipment necessary for wireless communication. By spinning these assets into a dedicated entity, Bell is following a global trend where telecommunications giants decouple their physical real estate from their service delivery operations.
Key Transaction Details:
- Stake Acquisition: La Caisse will hold a 49.9% minority interest, while Bell retains a 50.1% controlling stake.
- Valuation: The deal implies an enterprise value of $4.91 billion for the new infrastructure company.
- Asset Scope: TowerCo will own and operate over 5,000 sites across Canada, immediately becoming the country’s largest dedicated tower company.
- Operational Continuity: Bell will lease back capacity on these towers to maintain its network coverage. Importantly, Bell retains 100% ownership of its spectrum licenses, active network equipment (antennas, radios), and the land it currently owns.
- Financial Consolidation: Despite the minority sale, TowerCo’s financial results will remain consolidated within Bell’s financial statements. The new entity is expected to launch with zero financial debt.
The move is designed to provide Bell with immediate liquidity while ensuring it maintains operational control over the quality and reach of its award-winning wireless network.
II. Chronology: From Strategy to Execution
The seeds of this transaction were sown during BCE’s Investor Day in early 2025. During that presentation, the executive leadership team outlined a "Capital Allocation Strategy" aimed at navigating a high-interest-rate environment and the heavy capital expenditure requirements of 5G and fiber-to-the-home (FTTH) expansions.
Timeline of Events:
- Early 2025 (Investor Day): BCE announces a long-term goal to optimize its asset base, specifically targeting a net debt leverage ratio of 3.5x by the end of 2027.
- Mid-2025 to 2026: Internal restructuring begins to categorize "passive" vs. "active" infrastructure. Potential partners are vetted, with a focus on long-term institutional investors familiar with infrastructure lifecycles.
- Late 2026: Final negotiations with La Caisse (CDPQ) conclude, resulting in the definitive agreement.
- Q1 2027 (Projected): The transaction is expected to close, pending standard regulatory approvals from bodies such as the Competition Bureau and Innovation, Science and Economic Development (ISED) Canada.
This timeline reflects a disciplined approach to deleveraging. By announcing the deal well in advance of the 2027 debt target, BCE provides the market with a clear roadmap for its fiscal recovery and growth trajectory.
III. Supporting Data: Financial and Operational Metrics
The $2.45 billion price tag for a 49.9% stake highlights the premium valuation placed on Canadian digital infrastructure. To understand the scale of this deal, one must look at the underlying data that makes TowerCo a formidable player from day one.
The Power of 5,000 Sites
With over 5,000 sites, TowerCo will have a footprint that spans from the dense urban corridors of Toronto and Montreal to remote rural communities. In the world of telecommunications, "passive" assets are highly desirable for investors because they offer:
- Predictable Cash Flows: Long-term lease agreements with blue-chip tenants (like Bell).
- Low Maintenance Costs: Unlike active electronics, which require frequent upgrades, the physical tower structure has a long usable life.
- Colocation Upside: The ability to host multiple carriers on a single tower (e.g., Telus or Rogers leasing space on a TowerCo site) significantly increases the return on investment (ROI) per mast.
De-leveraging and Growth Funding
BCE has been under pressure to manage its debt-to-EBITDA ratio. The $2.45 billion in proceeds will be instrumental in:
- Reaching the 3.5x Leverage Target: Reducing interest expenses and improving credit ratings.
- AI and Innovation: BCE explicitly mentioned that the flexibility gained from this deal will fund "AI-powered solutions." This includes automating network management, enhancing customer service through generative AI, and optimizing predictive maintenance for the towers themselves.
IV. Official Responses: Leadership Perspectives
The leadership teams of BCE, La Caisse, and the newly formed TowerCo have expressed a unified vision for the partnership, though each emphasizes different strategic advantages.
Mirko Bibic, President and CEO of BCE and Bell Canada, framed the deal as a promise kept to shareholders:
"This partnership unlocks the significant value embedded in our infrastructure assets while continuing to operate the award-winning wireless network our customers rely on every day. As we have consistently communicated since early 2025, our approach is to strengthen our balance sheet, invest in growth and deliver total returns to shareholders."
Emmanuel Jaclot, Executive Vice-President at La Caisse, highlighted the efficiency and sustainability aspect of the deal:
"A telecom tower can carry more than one network. By making this infrastructure available to different service providers, we can strengthen coverage, improve overall system efficiency… Bell’s extensive footprint and La Caisse’s global digital infrastructure expertise will give this new platform the focus and long-term perspective to grow."
J. Bruce Furlong, CEO of TowerCo, emphasized the operational independence of the new entity:
"At TowerCo, we’re building a dedicated team exclusively focused on the development, operation and long-term growth of premier wireless tower infrastructure across Canada. By partnering with La Caisse on a clear mandate, we are well positioned to grow this infrastructure portfolio."
The rhetoric suggests a transition from a "closed" ecosystem, where Bell owned and used its towers exclusively, to an "open" infrastructure model that prioritizes asset utilization and national connectivity.
V. Implications: The Future of Canadian Telecom
The creation of TowerCo and the involvement of La Caisse carry profound implications for the Canadian market, ranging from competitive dynamics to the speed of 5G rollout.
1. Structural Separation as a Market Standard
This deal confirms that "structural separation"—the parting of services from infrastructure—is now the standard for major telcos. By offloading the "heavy lifting" of tower management to a dedicated entity, Bell can focus on being a software-driven service provider. We may see competitors like Telus or Rogers accelerate similar moves to stay competitive in their capital allocation.
2. Enhanced Competition and Shared Rural Networks
One of the most significant implications mentioned by Emmanuel Jaclot is "third-party colocation." Historically, Canadian carriers have been protective of their tower sites. However, as TowerCo seeks to grow its 49.9% stake value for La Caisse, it will be incentivized to lease space to any carrier. This could lead to:
- Reduced Capex for Smaller Players: Regional carriers may find it cheaper to lease space from TowerCo than to build their own masts.
- Better Rural Coverage: Shared infrastructure is often the only economically viable way to bring high-speed 4G and 5G to sparsely populated areas.
3. The Role of Institutional Capital in Digital Assets
La Caisse’s investment signals that digital infrastructure (towers, fiber, data centers) is now viewed with the same stability as traditional infrastructure like bridges or toll roads. For Canadian pensioners, whose funds are managed by CDPQ, this represents a stake in the literal backbone of the modern digital economy.
4. The AI Pivot
BCE’s mention of "AI-powered solutions" is a nod to the future. As 5G networks become more complex, managing them manually is becoming impossible. The capital from this deal allows Bell to invest in "Self-Healing Networks" and AI-driven traffic management, which are essential for the low-latency applications of the future, such as autonomous vehicles and remote surgery.
5. Regulatory Scrutiny
While the deal is expected to close in 2027, it will likely face intense scrutiny from Canadian regulators. The government will want to ensure that the creation of the "largest dedicated tower company" does not create a monopoly that could drive up leasing costs for smaller competitors, ultimately impacting consumer prices. However, since the deal encourages colocation and sharing, it may actually be viewed favorably as a way to improve national system efficiency.
Conclusion
BCE’s $2.45 billion agreement with La Caisse is a landmark moment in Canadian corporate history. It represents a sophisticated "win-win" scenario: Bell secures the capital necessary to shore up its balance sheet and invest in the AI-driven future, while La Caisse gains a massive, stable, and essential asset class in the form of TowerCo.
As the transaction moves toward its 2027 closing date, the industry will be watching closely. The success of TowerCo could redefine how connectivity is delivered in Canada, moving the needle from a landscape of proprietary silos to one of shared, efficient, and highly capitalized digital infrastructure. For the Canadian consumer, the end result should be a more robust, reliable, and technologically advanced network that powers the next generation of digital innovation.